
Creating a balance sheet is an essential task for any business owner or financial professional. This document provides a snapshot of a company’s financial health at a specific point in time, detailing what the company owns (assets), what it owes (liabilities), and the equity held by its shareholders. Understanding how to craft a perfect balance sheet is crucial for evaluating the financial stability and performance of a business. This article will guide you through the process of creating a balance sheet, explaining the key components and their significance. We’ll explore the structure of a balance sheet, the types of assets and liabilities to include, and how to calculate shareholders’ equity, ensuring you have a comprehensive understanding of what makes a balance sheet both accurate and insightful. Additionally, we will discuss common mistakes to avoid and how to use the balance sheet for financial analysis, making it a powerful tool for managing your business.
Understanding the Balance Sheet
A balance sheet, also known as a statement of financial position, is one of the three fundamental financial statements used to assess a company’s financial health, alongside the income statement and cash flow statement. The balance sheet provides a detailed overview of a company’s assets, liabilities, and shareholders’ equity at a specific point in time. The core principle of a balance sheet is that it must balance, meaning the total assets must equal the total liabilities plus shareholders’ equity. This balance ensures that all financial resources and obligations are accurately accounted for. The balance sheet formula is typically expressed as: Assets = Liabilities + Shareholders’ Equity. This equation underpins the entire balance sheet, ensuring that every financial transaction is properly recorded and categorized. This foundational understanding is crucial for anyone involved in financial management, as it helps maintain accuracy and transparency in financial reporting.
Assets: What the Company Owns
Assets are the resources owned by the company that have economic value and can be converted into cash. They are divided into two main categories: current assets and non-current assets. Current assets are expected to be converted into cash or used up within one year and include items such as cash and cash equivalents, accounts receivable, inventory, and prepaid expenses. These assets are vital for day-to-day operations, ensuring the company can meet its short-term obligations. Non-current assets, also known as long-term assets, are those that are expected to provide economic benefits beyond one year. These include property, plant, and equipment (PP&E), intangible assets like patents and trademarks, and long-term investments. Properly categorizing and valuing assets is crucial for providing an accurate picture of the company’s financial position. For instance, understanding the difference between tangible assets (like machinery and real estate) and intangible assets (such as intellectual property) helps in evaluating the true value and operational capacity of a business.
Liabilities: What the Company Owes
Liabilities represent the company’s financial obligations—what it owes to others. Like assets, liabilities are classified as either current or non-current. Current liabilities are obligations that are due within one year, such as accounts payable, short-term loans, and accrued expenses. These liabilities are critical for assessing the company’s short-term financial health and its ability to meet immediate financial obligations. Non-current liabilities are long-term obligations that are due beyond one year, including long-term debt, deferred tax liabilities, and pension obligations. Accurately listing liabilities is essential for understanding the company’s financial responsibilities and ensuring that it has the resources to meet its obligations. Properly managing and categorizing liabilities can also help in planning for future financial needs and maintaining healthy cash flow. For example, long-term liabilities might include bonds payable, which represent a significant future obligation that needs careful financial planning to manage.
Shareholders’ Equity: The Owners’ Claims
Shareholders’ equity, also known as owner’s equity or stockholders’ equity, represents the owners’ residual interest in the company after liabilities have been deducted from assets. It includes common stock, preferred stock, retained earnings, and additional paid-in capital. Retained earnings are the accumulated profits that have been reinvested in the business rather than distributed to shareholders as dividends. Shareholders’ equity can be calculated using the formula: Shareholders’ Equity = Total Assets – Total Liabilities. This section of the balance sheet reflects the net worth of the company and indicates the financial health and stability of the business. It is a critical measure for investors and stakeholders to assess the company’s value and growth potential. The equity section also provides insights into how well the company has been managed over time, showcasing the profits retained within the business versus those distributed as dividends.
Preparing the Balance Sheet
To prepare a balance sheet, start by determining the reporting date and period. This is typically the end of an accounting period, such as the end of a fiscal quarter or year. The reporting date is crucial as it provides a specific snapshot in time of the company’s financial status. Next, list all the company’s assets and categorize them as current or non-current. Total the assets to get the sum of current and non-current assets. Then, list all liabilities, again categorizing them as current or non-current, and total them. Finally, calculate shareholders’ equity by subtracting total liabilities from total assets. Ensure that the balance sheet balances by verifying that total assets equal the sum of total liabilities and shareholders’ equity. This step-by-step approach helps ensure accuracy and completeness in financial reporting. Using accounting software can simplify this process, reducing the risk of human error and ensuring that all financial data is accurately recorded and categorized.
Common Balance Sheet Mistakes
Creating a balance sheet can be complex, and common mistakes include incomplete or misplaced data, incorrect entries, and errors in currency exchange rates or inventory valuation. It’s essential to regularly review and audit the balance sheet to identify and correct these errors. Miscalculations in loan amortization or depreciation can also cause imbalances. Ensuring accuracy in these areas is crucial for maintaining the integrity of the financial statements. Regular audits and the use of reliable accounting software can help mitigate these risks and ensure that the balance sheet accurately reflects the company’s financial position. Additionally, understanding and applying the correct accounting principles, such as Generally Accepted Accounting Principles (GAAP) or International Financial Reporting Standards (IFRS), is essential for maintaining consistency and accuracy in financial reporting.
Using the Balance Sheet for Financial Analysis
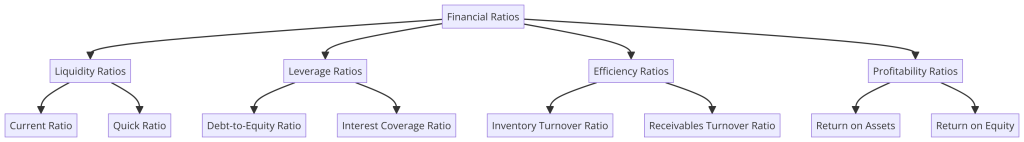
A balance sheet is not just a static document; it is a powerful tool for financial analysis. By comparing current assets to current liabilities, you can assess the company’s liquidity and its ability to meet short-term obligations. Calculating financial ratios such as the current ratio, quick ratio, and debt-to-equity ratio provides deeper insights into the company’s financial health. For example, the current ratio (current assets divided by current liabilities) measures liquidity, while the debt-to-equity ratio (total liabilities divided by shareholders’ equity) assesses financial leverage. These metrics are valuable for investors, creditors, and management to make informed decisions about the company’s operations and strategies. Additionally, analyzing trends over multiple periods can provide insights into the company’s performance and financial stability over time. This continuous monitoring and analysis help in strategic planning and decision-making, ensuring the business remains financially healthy and competitive.
In conclusion, crafting the perfect balance sheet involves understanding and accurately reporting a company’s assets, liabilities, and shareholders’ equity. This financial statement is crucial for assessing the financial health and performance of a business. By ensuring that the balance sheet balances and by using it for financial analysis, businesses can gain valuable insights into their operations and make informed strategic decisions. Regular reviews and audits are essential for maintaining the accuracy and reliability of the balance sheet. Understanding the components and purpose of a balance sheet empowers business owners and financial professionals to effectively manage their company’s finances and achieve long-term success. With a well-prepared balance sheet, companies can not only assess their current financial position but also plan for future growth and stability, ensuring they are well-equipped to handle financial challenges and opportunities.